
 NewsSical Logistics wins Rs 39.23 crore work order from Steel Authority of India Limited for iron ore excavation
Sical Logistics wins Rs 39.23 crore work order from Steel Authority of India Limited for iron ore excavation


- Sical Logistics wins Rs 39.23 Cr confirmed work order from Steel Authority of India Limited for iron ore excavation.
- Total disclosed order book stands at Rs 534.73 Cr, providing 4.04 quarters of coverage based on average quarterly revenue.
- FY26 revenue grew by 75.4% YoY, but free cash flow remained negative at -Rs 51.10 Cr due to high capex.
- Working capital pressure is evident with a Current Ratio of 1.12x and Total Liabilities/Equity of 2.37x.

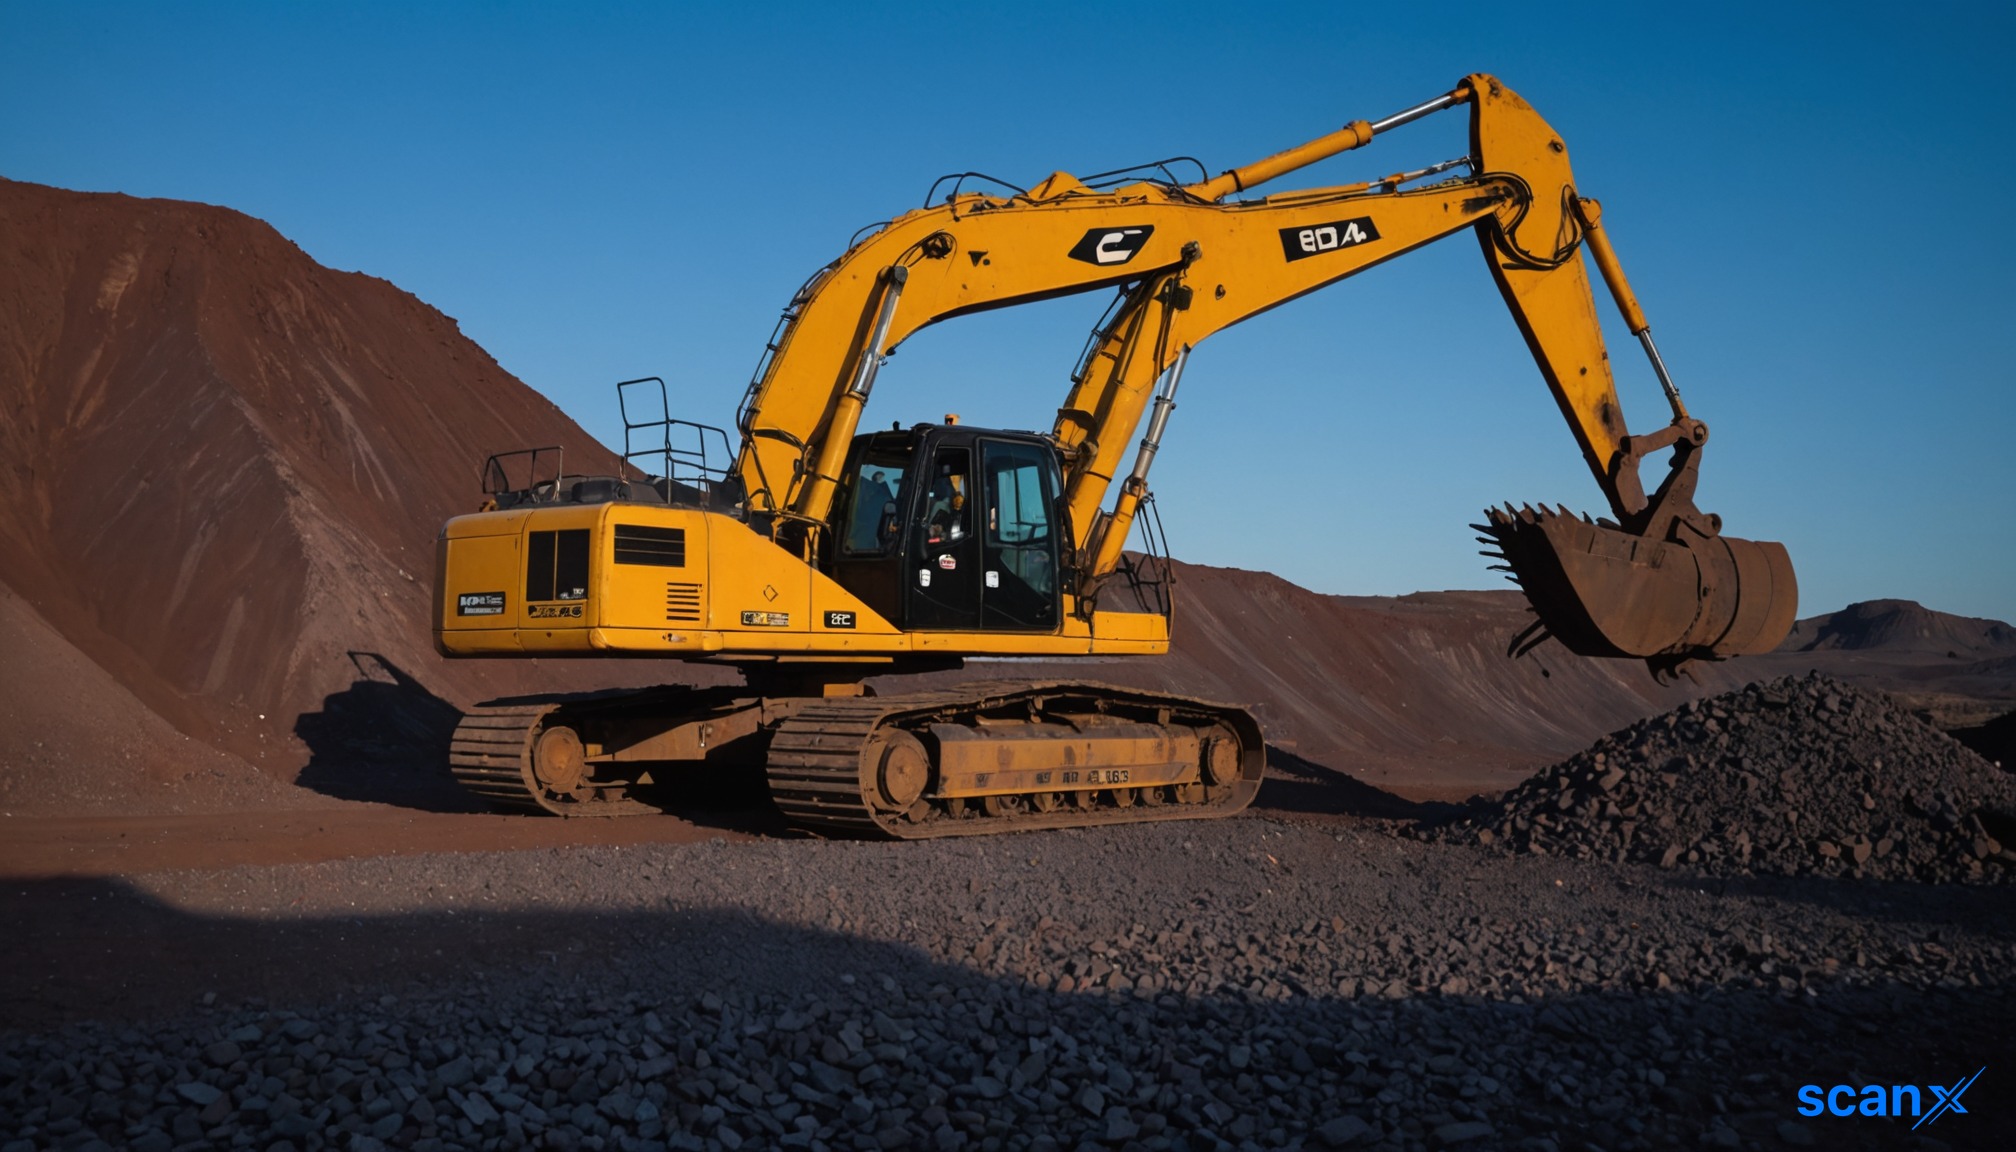

*this image is generated using AI for illustrative purposes only.
Sical Logistics has received a confirmed work order valued at Rs 39.23 crore from Steel Authority of India Limited for excavation and transportation of iron ore, ICW, and subgrade ore at Dalli Mech Mine Phase #6.
The contract period extends from October 5, 2026, to November 18, 2028. This filing is classified as a significant order under SEBI LODR Regulation 30, indicating immediate executability rather than a pre-qualification or mobilisation notice.
Order in Financial Context
The Rs 39.23 crore order value represents approximately 29.7% of the company’s average quarterly revenue of Rs 132.28 Cr. When combined with recent disclosures, the total disclosed order book stands at Rs 534.73 Cr across 1 orders (sum of the 1 orders disclosed across the last 3 fiscal quarters shown in the table below). This backlog provides order book coverage of 4.04 quarters based on current run-rates. It is important to note that this specific SAIL order was disclosed on October 5, 2026, falling into Q3FY27, while the pre-computed order book figure reflects the prior quarter's major inflow.
Company Order Track Record
Order inflow velocity remains robust, driven by large-scale mining contracts. The recent history shows a singular but massive inflow in the previous quarter, contrasting with the smaller, incremental addition from SAIL in the current period. The per-order size of the SAIL contract is significantly lower than the typical mega-projects seen in the recent history, suggesting a diversification of client base or project scale.
| Quarter | Total Order Inflow (Rs Cr) | Key Awarding Entities |
|---|---|---|
| Q2FY27 (Jul-Sep 2026) | 534.73 | M/s Central Coalfields Limited |
Execution and Revenue Quality
Recent quarterly performance indicates volatility in net profit despite stable operating margins. Q1FY27 showed healthy profitability with a net profit of Rs 21.20 Cr, while Q4FY26 recorded a net loss of Rs 8.80 Cr. Operating Profit Margins have remained relatively consistent between 18% and 19%, suggesting stable execution costs.
| Quarter | Revenue (Rs Cr) | Net Profit (Rs Cr) | OPM (%) |
|---|---|---|---|
| Q1FY27 | 151.20 | 21.20 | 18.83% |
| Q4FY26 | 106.90 | -8.80 | 18.47% |
| Q3FY26 | 151.60 | 47.90 | 19.16% |
Revenue Growth: Order Wins Translating to Revenue
As Sical Logistics has sustained order wins, particularly with the major Central Coalfields Limited contract in Q2FY27, its annual revenue has grown from Rs 240.90 crore in FY25 to Rs 422.60 crore in FY26, representing a YoY growth of +75.4% based on the latest annual data. This surge aligns with the increased execution activity visible in the balance sheet expansion.
Working Capital and Execution Capacity
The company faces tight liquidity conditions with a Current Ratio of 1.12x, which is below the comfortable threshold of 1.2x. Total Liabilities/Equity stands at 2.37x, indicating elevated leverage when considering all liabilities. Although Operating Cashflow improved to Rs 52.30 Cr in FY26, Free Cash Flow remained negative at -Rs 51.10 Cr due to high capital expenditure of Rs 103.40 Cr. This suggests that while operations are generating cash, heavy reinvestment is consuming it, potentially straining the ability to fund working capital cycles for new orders without external financing.
What to Watch
- Execution Rate: Monitor quarterly revenue conversion against the Rs 534.73 Cr backlog; acceleration is needed to justify the current valuation multiples.
- Margin Quality: Watch if OPM sustains above 18% as the new SAIL contract executes, especially given the historical volatility in net profit.
- Client Concentration: The order book is heavily concentrated with M/s Central Coalfields Limited accounting for the entirety of the disclosed Rs 534.73 Cr backlog, creating single-client dependency risk.
- Working Capital Stress: Given the 1.12x current ratio, any delay in receivables collection could impact liquidity for ongoing projects.
Key Observations
- Backlog signal: Book-to-bill context shows order book coverage of 4.04 quarters. At this level, execution capacity becomes the binding constraint for realizing value.
- Leverage flag: Total Liabilities/Equity of 2.37x; balance sheet carries elevated liabilities, and ability to fund working capital for the existing backlog should be monitored.
- Cash conversion: Free cash flow of -Rs 51.10 Cr in FY26; backlog is not converting to cash efficiently after capex, and the working capital cycle may be stretched.
- Valuation check (as of 04 Oct 2026): P/E of 9.9x against ROCE of 17.42%. At the time of this article, valuation was pricing in execution improvement not yet fully visible in return ratios relative to peers.
Historical Stock Returns for Sical Logistics
| 1 Day | 5 Days | 1 Month | 6 Months | 1 Year | 5 Years |
|---|---|---|---|---|---|
| -4.51% | -7.72% | -16.81% | +38.20% | 0.0% | +759.62% |

 15






 Access 50+ Readymade Screeners
 Use 200+ Custom Filters
 Get Full Market Insights





