

Jain Irrigation Systems Dvr receives Rs 117.96 crore empanelment from MSEDCL


- Jain Irrigation Systems Dvr received a Letter of Empanelment worth Rs 117.96 crore from MSEDCL.
- The empanelment covers 5,000 Off-Grid DC Solar Photovoltaic Water Pumping Systems across Maharashtra.
- This is a pre-qualification status; revenue recognition requires formal work orders.
- The order book coverage stands at 0.07 quarters of average quarterly revenue.
- The company faces high interest expenses of Rs 746.5 crore annually, impacting net profitability.

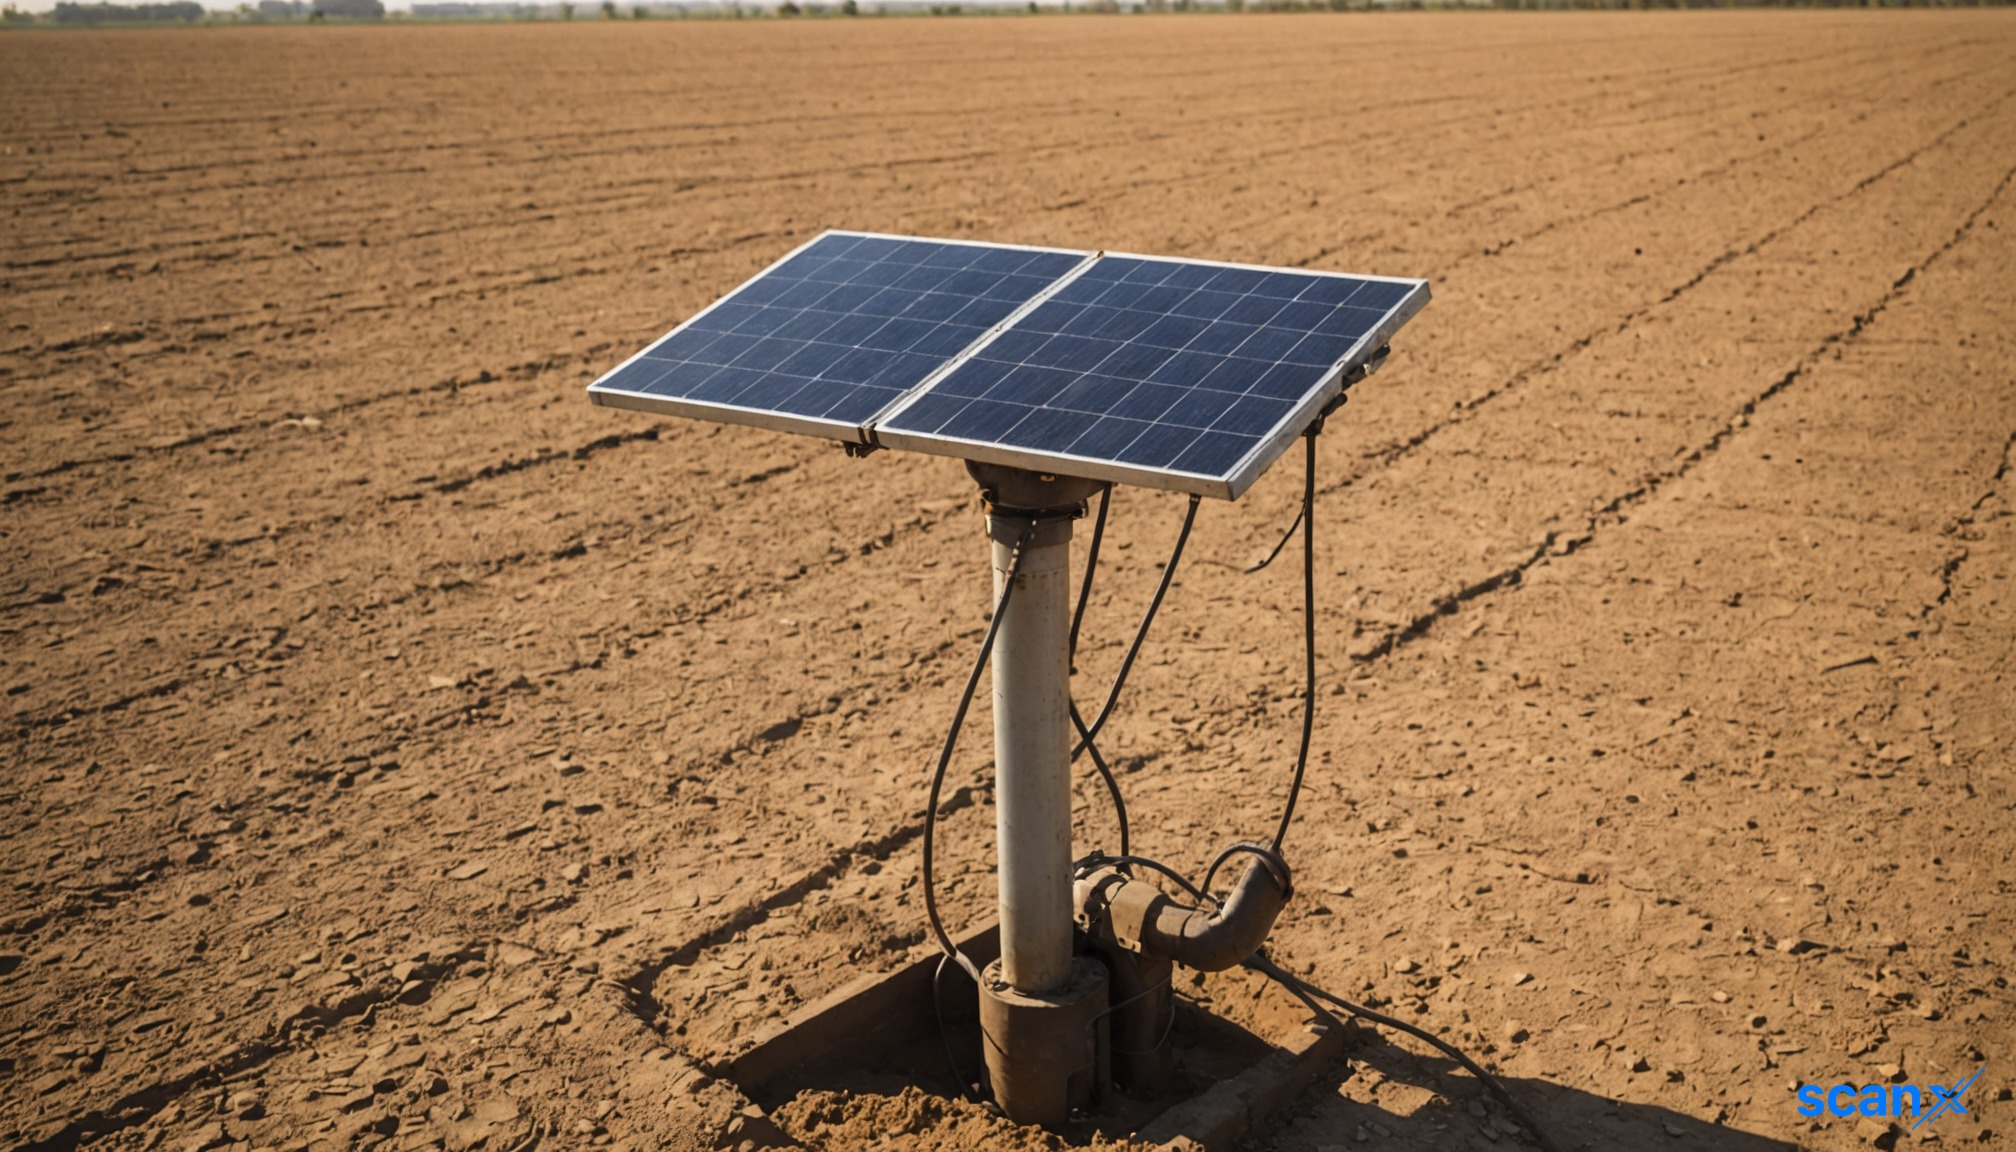

*this image is generated using AI for illustrative purposes only.
Jain Irrigation Systems Dvr received a Letter of Empanelment worth Rs 117.96 crore from Maharashtra State Electricity Distribution Company Limited (MSEDCL). This is a pre-qualification status, not a confirmed work order.
WHAT HAPPENED
The company was empanelled for supplying and installing 5,000 Off-Grid DC Solar Photovoltaic Water Pumping Systems across Maharashtra under the Magel Tyala Saur Krushi Pump Yojana. The scope includes design, manufacture, transportation, installation, testing, and commissioning of agricultural solar pumps with capacities of 3 HP, 5 HP, and 7.5 HP. The time period cited is 60 days, likely referring to the validity or mobilization window for this empanelment phase.
ORDER IN FINANCIAL CONTEXT
The Rs 117.96 crore empanelment value represents approximately 7% of the company's average quarterly revenue of Rs 1662.57 crore. The total disclosed order book coverage is 0.07 quarters of average quarterly revenue (sum of the 1 orders disclosed across the last 3 fiscal quarters shown in the table below). Since this is a Letter of Empanelment, it signifies eligibility to bid or receive future work orders rather than a binding contract. Revenue recognition will only begin after formal work orders are issued against this empanelment.
COMPANY ORDER TRACK RECORD
The company has disclosed one order in the last three fiscal quarters.
| Quarter | Total Order Inflow (Rs Cr) | Key Awarding Entities |
|---|---|---|
| Q2FY27 (Jul-Sep 2026) | 117.96 (1 orders) | Maharashtra State Electricity Distribution Company Limited |
EXECUTION AND REVENUE QUALITY
In Q3FY22, the company reported revenue of Rs 1645.20 crore and an operating profit margin of 6.66%. However, net profit turned negative at -Rs 72.00 crore, signaling execution stress likely driven by high interest costs or one-time charges. In the preceding two quarters, OPM was healthier at 10.28% and 14.73%, indicating a decline in operational efficiency recently.
| Quarter | Revenue (Rs Cr) | Net Profit (Rs Cr) | OPM (%) |
|---|---|---|---|
| Q3FY22 | 1645.20 | -72.00 | 6.66% |
| Q2FY22 | 1885.20 | 108.20 | 10.28% |
| Q1FY22 | 1777.50 | 13.40 | 14.73% |
WORKING CAPITAL AND EXECUTION CAPACITY
The company faces significant leverage challenges. Annual interest expenses stand at Rs 746.5 crore, which substantially outweighs the annual EBITDA of Rs 892.2 crore. This high interest burden explains the net losses despite positive operating profits. With a microcap market capitalization of Rs 41.97 crore (as of 17 Sep 2026) and a Price/Book ratio of 0.03x (as of 17 Sep 2026), the balance sheet appears stretched. Investors must monitor whether the company can secure working capital to execute any future orders derived from this empanelment without further diluting equity or increasing debt.
WHAT TO WATCH
- Formal Work Orders: Revenue recognition depends on MSEDCL issuing specific work orders against this empanelment. Track disclosures for actual LOAs.
- Interest Burden: Annual interest of Rs 746.5 crore remains a critical drag on profitability. Any reduction in debt or interest rates would directly impact net margins.
- OPM Recovery: Operating profit margins have declined from 14.73% in Q1FY22 to 6.66% in Q3FY22. Watch for stabilization in operational efficiency.
- Client Concentration: MSEDCL is a key state utility. Success in securing large-scale solar pump contracts here could provide scale, but reliance on government schemes carries policy risk.
KEY OBSERVATIONS
- Contract structure: This is a Letter of Empanelment. Revenue recognition begins only after formal work order issuance. The Rs 117.96 crore represents potential business volume, not a confirmed contract value.
- Margin stress: Net loss of Rs 72.00 crore in Q3FY22; execution stress visible in quarterly data due to high interest costs.
- Valuation check (as of 17 Sep 2026): P/E of 0.0x against ROCE of 0%. At the time of this article, valuation reflects negative earnings and zero returns on capital employed.
- Cash conversion: High interest expenses of Rs 746.5 crore relative to EBITDA of Rs 892.2 crore indicate that operating cashflows are heavily consumed by debt servicing, limiting free cashflow generation.
Historical Stock Returns for Jain Irrigation Systems DVR
| 1 Day | 5 Days | 1 Month | 6 Months | 1 Year | 5 Years |
|---|---|---|---|---|---|
| -1.44% | -6.28% | -5.79% | -9.03% | -41.05% | -12.94% |

 16




 Access 50+ Readymade Screeners
 Use 200+ Custom Filters
 Get Full Market Insights





