

Green Asia Impex IPO DRHP: ₹40.03 crore fresh issue for capex; revenue at ₹383.80 Cr


- Fresh issue of ₹40.03 crore to fund new seafood processing facility in Chinnayagudem
- Revenue grew to ₹383.80 Cr in FY2026; PAT rose to ₹15.61 Cr
- Negative operating cash flows reported for FY2024, FY2025, and FY2026
- China accounts for 31.29% of revenue; top 10 customers contribute 77.85%
- Issue opens 24-Sep-2026; listing scheduled for 01-Oct-2026

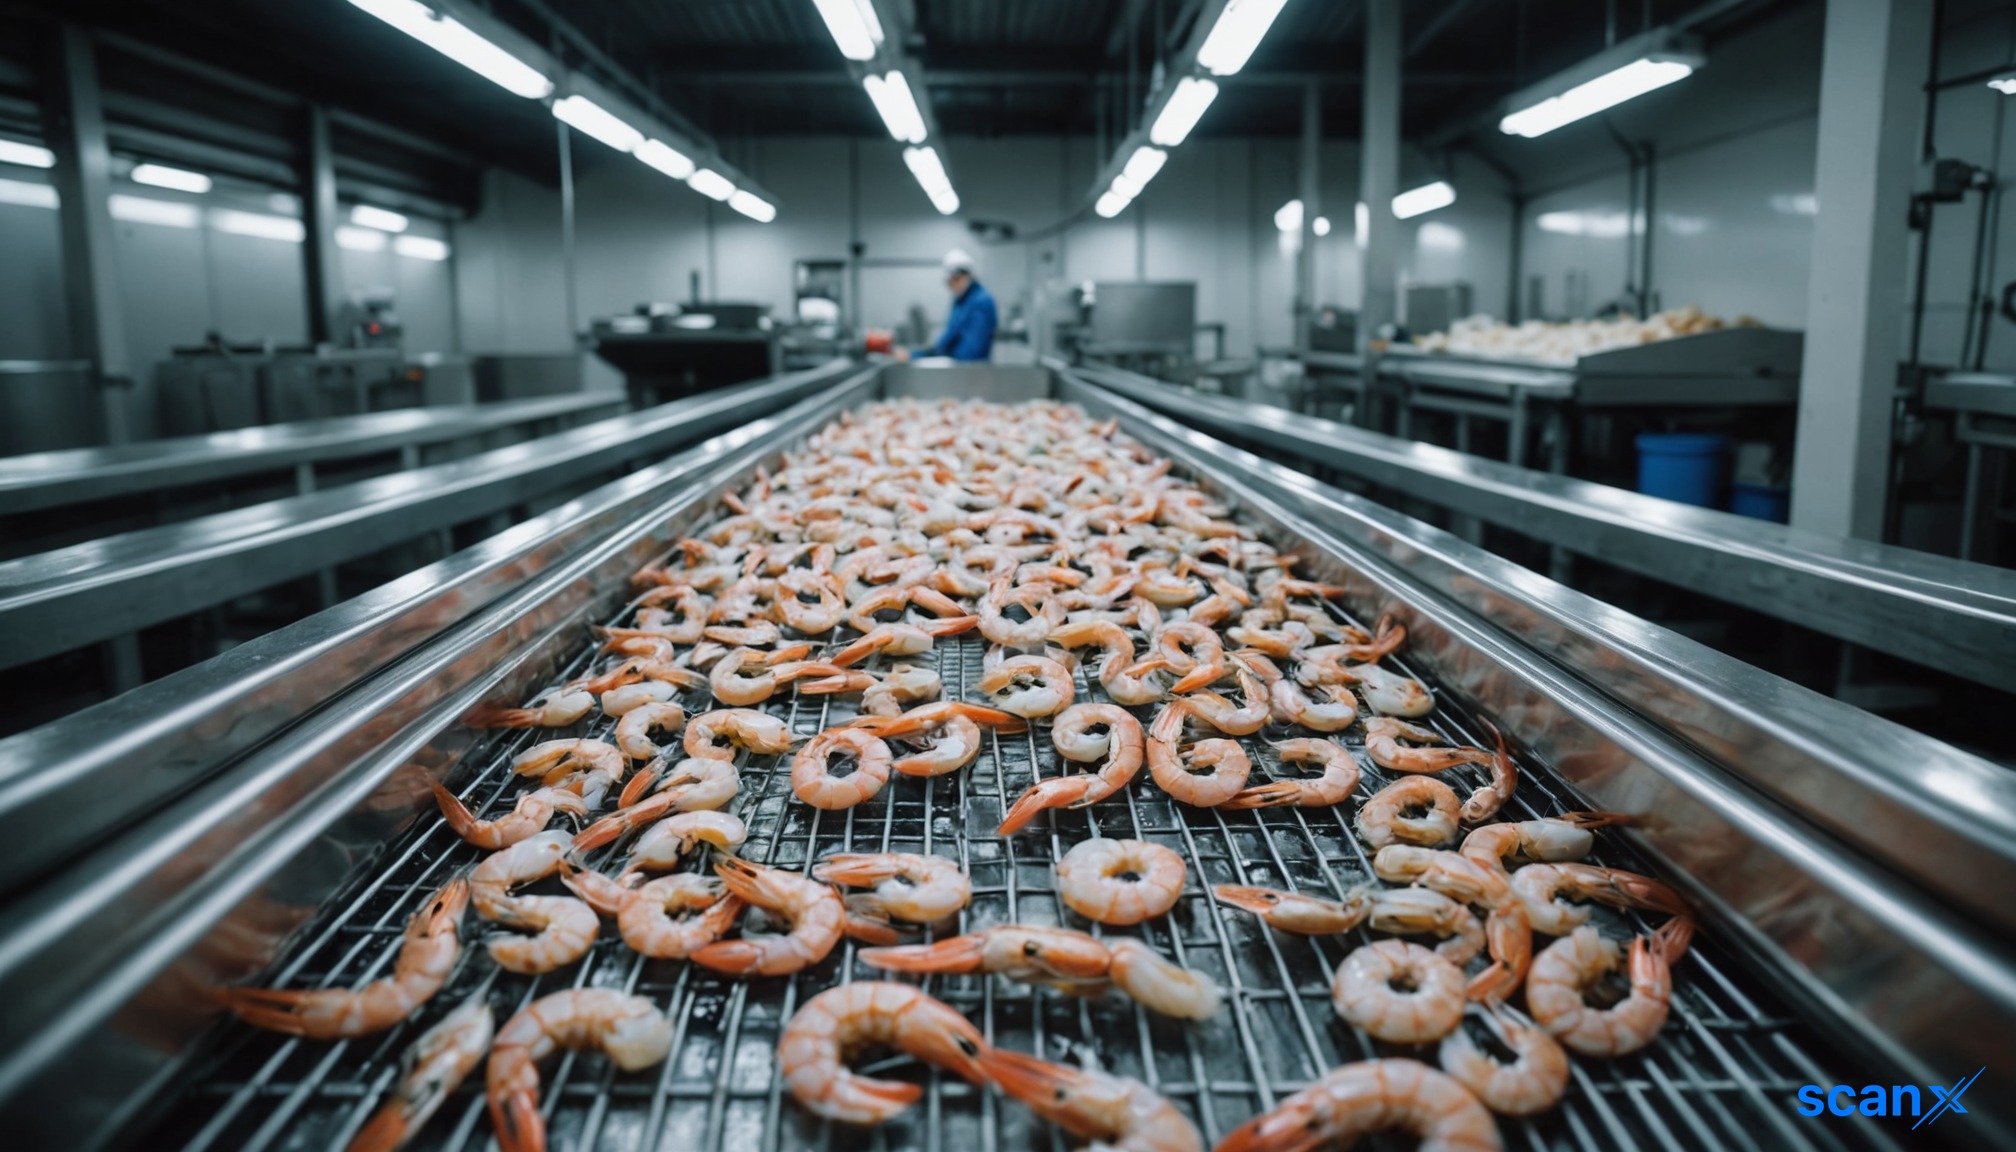

*this image is generated using AI for illustrative purposes only.
Green Asia Impex Limited, an Andhra Pradesh-based export house specializing in frozen seafood and agri-commodities, has filed its Draft Red Herring Prospectus (DRHP) for an SME IPO. The company proposes a fresh issue of ₹40.03 crore to fund capital expenditure for a new processing facility, seeking to expand its installed capacity from 10,800 MTPA to approximately 21,900 MTPA.
About the Company
Incorporated in 2014 and headquartered in Tadepalligudem, Green Asia Impex operates as a Two Star Export House recognized by the Directorate General of Foreign Trade (DGFT). The company sources, processes, and exports frozen shrimps and dried chillies to B2B customers across seven countries, including China, the USA, Kuwait, Malaysia, the UK, Vietnam, and Thailand.
The business is divided into two primary segments. Frozen shrimps, including Vannamei, Black Tiger, and Freshwater varieties in HOSO, HLSO, and PD formats, accounted for 87.76% of FY2026 revenue from operations. Dried chillies, such as Teja, Bydagi, and Guntur Sannam, constitute the balance. The company maintains a semi-automated facility equipped with grading machines, plate freezers, and IQF hardeners, holding certifications including HACCP, ISO 22000, FSSAI, FDA registration, and GACC.
Financial Performance
The company has demonstrated consistent top-line growth over the last three fiscal years. Revenue from operations increased from ₹317.39 crore in FY2024 to ₹383.80 crore in FY2026, reflecting a compound annual growth rate of approximately 9.90%. Profit After Tax (PAT) improved significantly from ₹6.66 crore in FY2024 to ₹15.61 crore in FY2026, with PAT margins expanding from 2.09% to 4.01%.
| Metric | FY2024 (₹ Cr) | FY2025 (₹ Cr) | FY2026 (₹ Cr) |
|---|---|---|---|
| Revenue from Operations | 317.39 | 337.62 | 383.80 |
| Total Revenue | 318.15 | 339.65 | 388.63 |
| Profit Before Tax (PBT) | 9.03 | 14.39 | 21.04 |
| Profit After Tax (PAT) | 6.66 | 10.35 | 15.61 |
| Total Assets | 135.23 | 192.04 | 254.88 |
| Total Equity | 15.46 | 25.81 | 41.43 |
Despite accounting profits, the company reported negative operating cash flows in all three fiscal years: ₹(15.00) crore in FY2024, ₹(5.06) crore in FY2025, and ₹(6.27) crore in FY2026. This trend indicates that operations are being funded through financing activities, with total borrowings standing at ₹9,946.76 lakhs as of FY2026. Trade receivables also increased significantly, rising from ₹2,573.58 lakhs in FY2024 to ₹9,735.48 lakhs in FY2026, pushing receivable days from 26 to 77 days.
Why the Company Is Raising Funds
The entire net proceeds from the fresh issue are designated for funding capital expenditure related to setting up a proposed seafood processing facility at Chinnayagudem, Andhra Pradesh. The total cost of this project is estimated at ₹5,126.94 lakhs, with ₹40.03 crore allocated from IPO proceeds to cover plant, machinery, and equipment purchases. A portion of general corporate purposes, capped at 15% of gross proceeds, will support working capital and raw material purchases.
Business Strengths
The company benefits from strong client retention, with repeat customer revenue contributing ₹28,382.97 lakhs, or 73.95%, of FY2026 revenue. Its export-grade facilities comply with global standards, facilitating access to premium markets in the USA, UK, and China. Additionally, the complementary seasonal cycles of shrimp (October–July) and chillies (January–April) help mitigate operational downtime and revenue seasonality.
Key Risks
Material risks disclosed include significant revenue concentration in China, which accounted for 31.29% of FY2026 revenue from operations. Adverse geopolitical or regulatory changes in this market could impact earnings. The company also faces high customer concentration, with the top 10 customers representing 77.85% of FY2026 revenue, and no long-term agreements are in place to secure these orders.
Financially, the persistent negative operating cash flows and elevated debt-to-equity ratio of 2.40x pose liquidity challenges. Furthermore, 100% of the capex funded by net proceeds, amounting to ₹3,240.86 lakhs, has not yet been ordered, introducing execution risk regarding timelines and cost overruns. A contingent liability of ₹788.69 lakhs related to an income tax demand for FY2021-22 remains under appeal.
Important IPO Dates
The issue opens on 24-Sep-2026 and closes on 28-Sep-2026. Allotment is scheduled for 29-Sep-2026, with listing expected on 01-Oct-2026. Specific price band and lot size details were not available in the provided data.
Bottom Line
Green Asia Impex presents a growth story anchored by expanding revenue and improving margins, supported by a robust export network and DGFT recognition. However, the investment thesis is tempered by structural financial concerns, including three years of negative operating cash flows, high leverage, and significant concentration risks in both geography and customer base. The success of the IPO-funded capacity expansion will be critical to addressing working capital pressures and sustaining profitability.

How will the company manage the significant working capital strain from rising trade receivables while executing the ₹51 crore capex project?
What specific strategies is Green Asia Impex implementing to diversify its revenue base and reduce its 31% dependency on Chinese exports?
Given the persistent negative operating cash flows, how does management plan to service the elevated debt burden if the new facility faces commissioning delays?
 20




 Create Custom Screeners
 Access 200+ Pre-built Filters
 Use 50+ Readymade Screener





