Seamec vessel SAMUDRA PRABHA recused for statutory drydocking

scanx
Reviewed by
Shriram SScanX News Team
Key Highlights
  • Vessel SAMUDRA PRABHA recused from project on October 5, 2026
  • Recusal effective from 4:00 am for statutory drydocking
  • Vessel is owned by ONGC and managed by Seamec Limited
  • Disclosure made under Regulation 30 of SEBI LODR Regulations
powered bylight_fuzz_icon
52730141

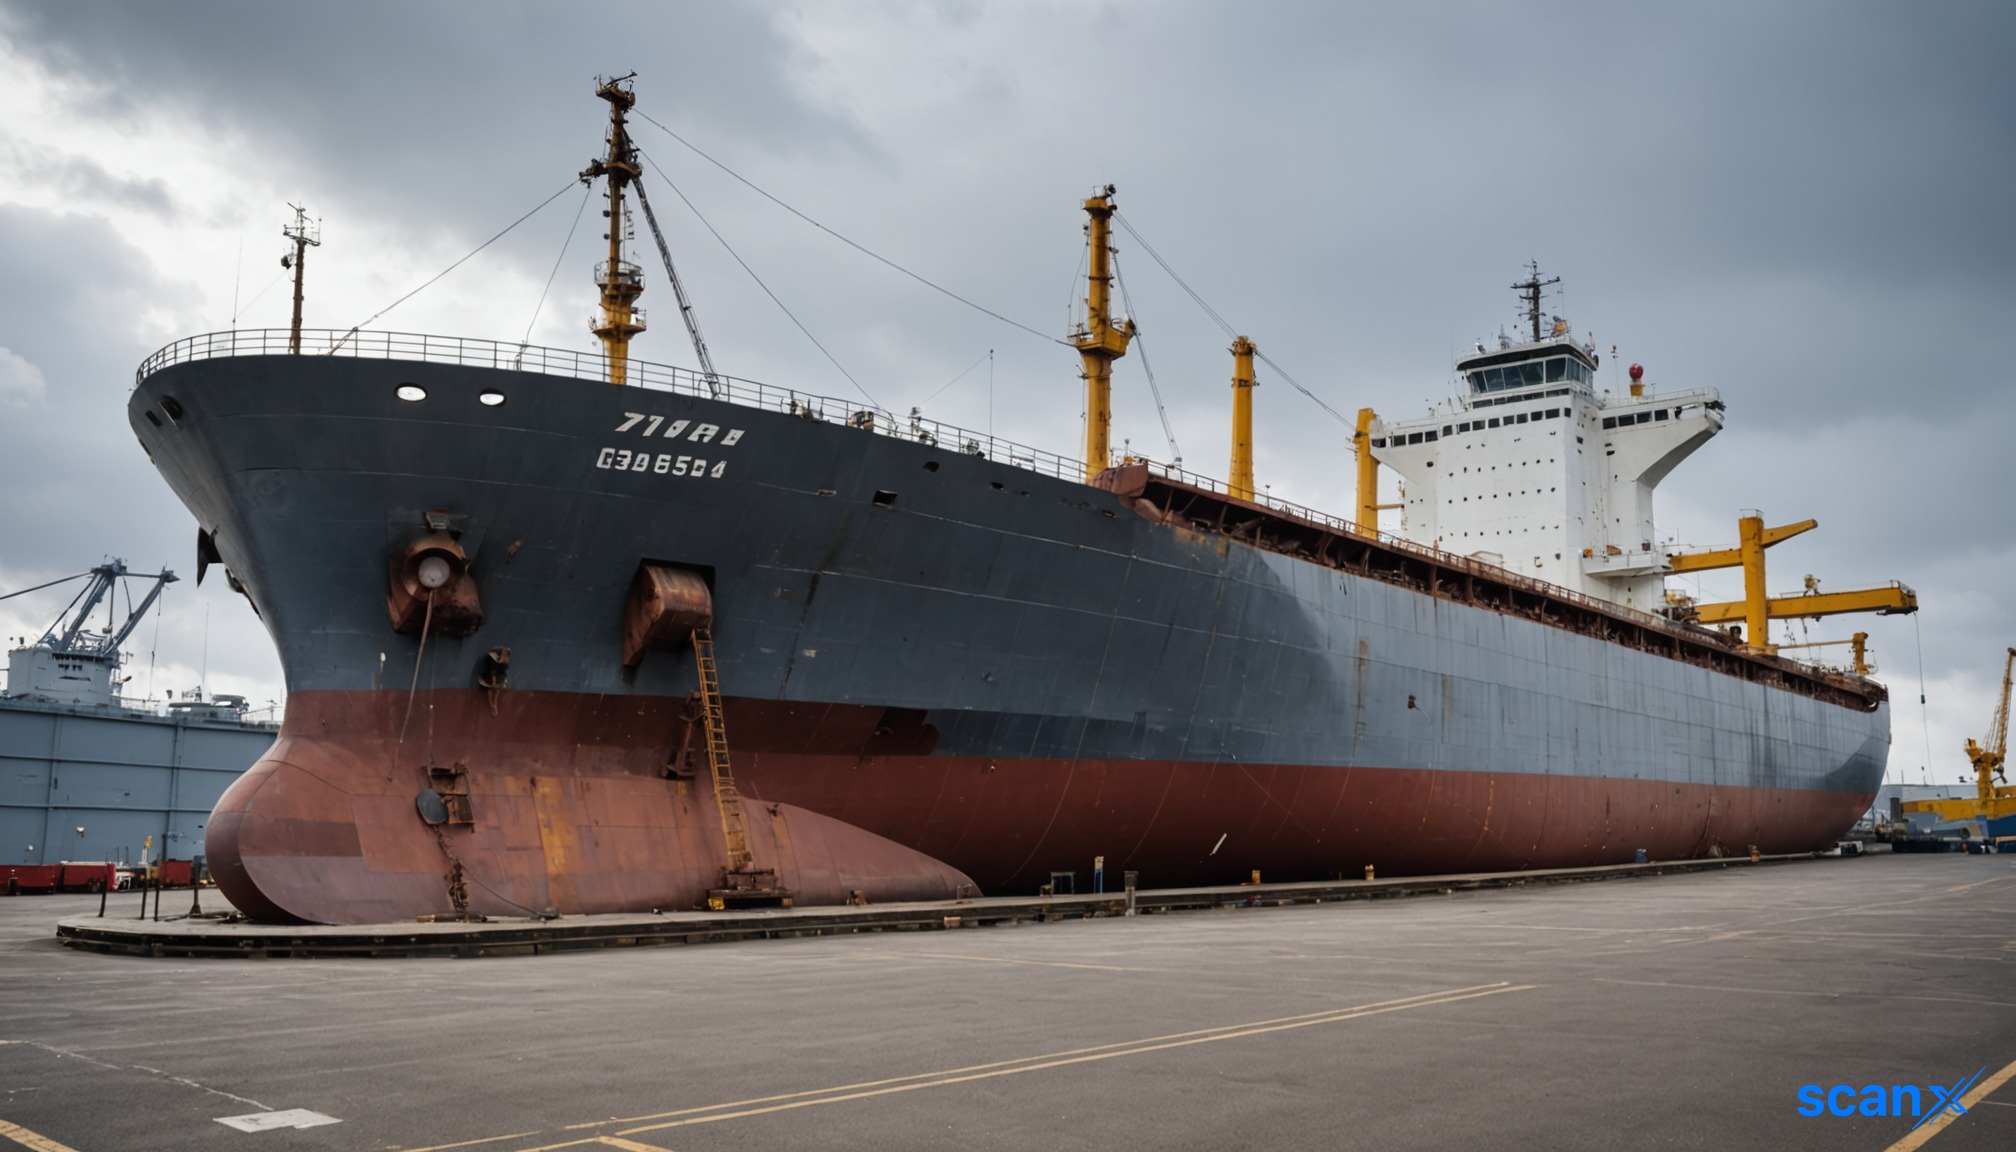
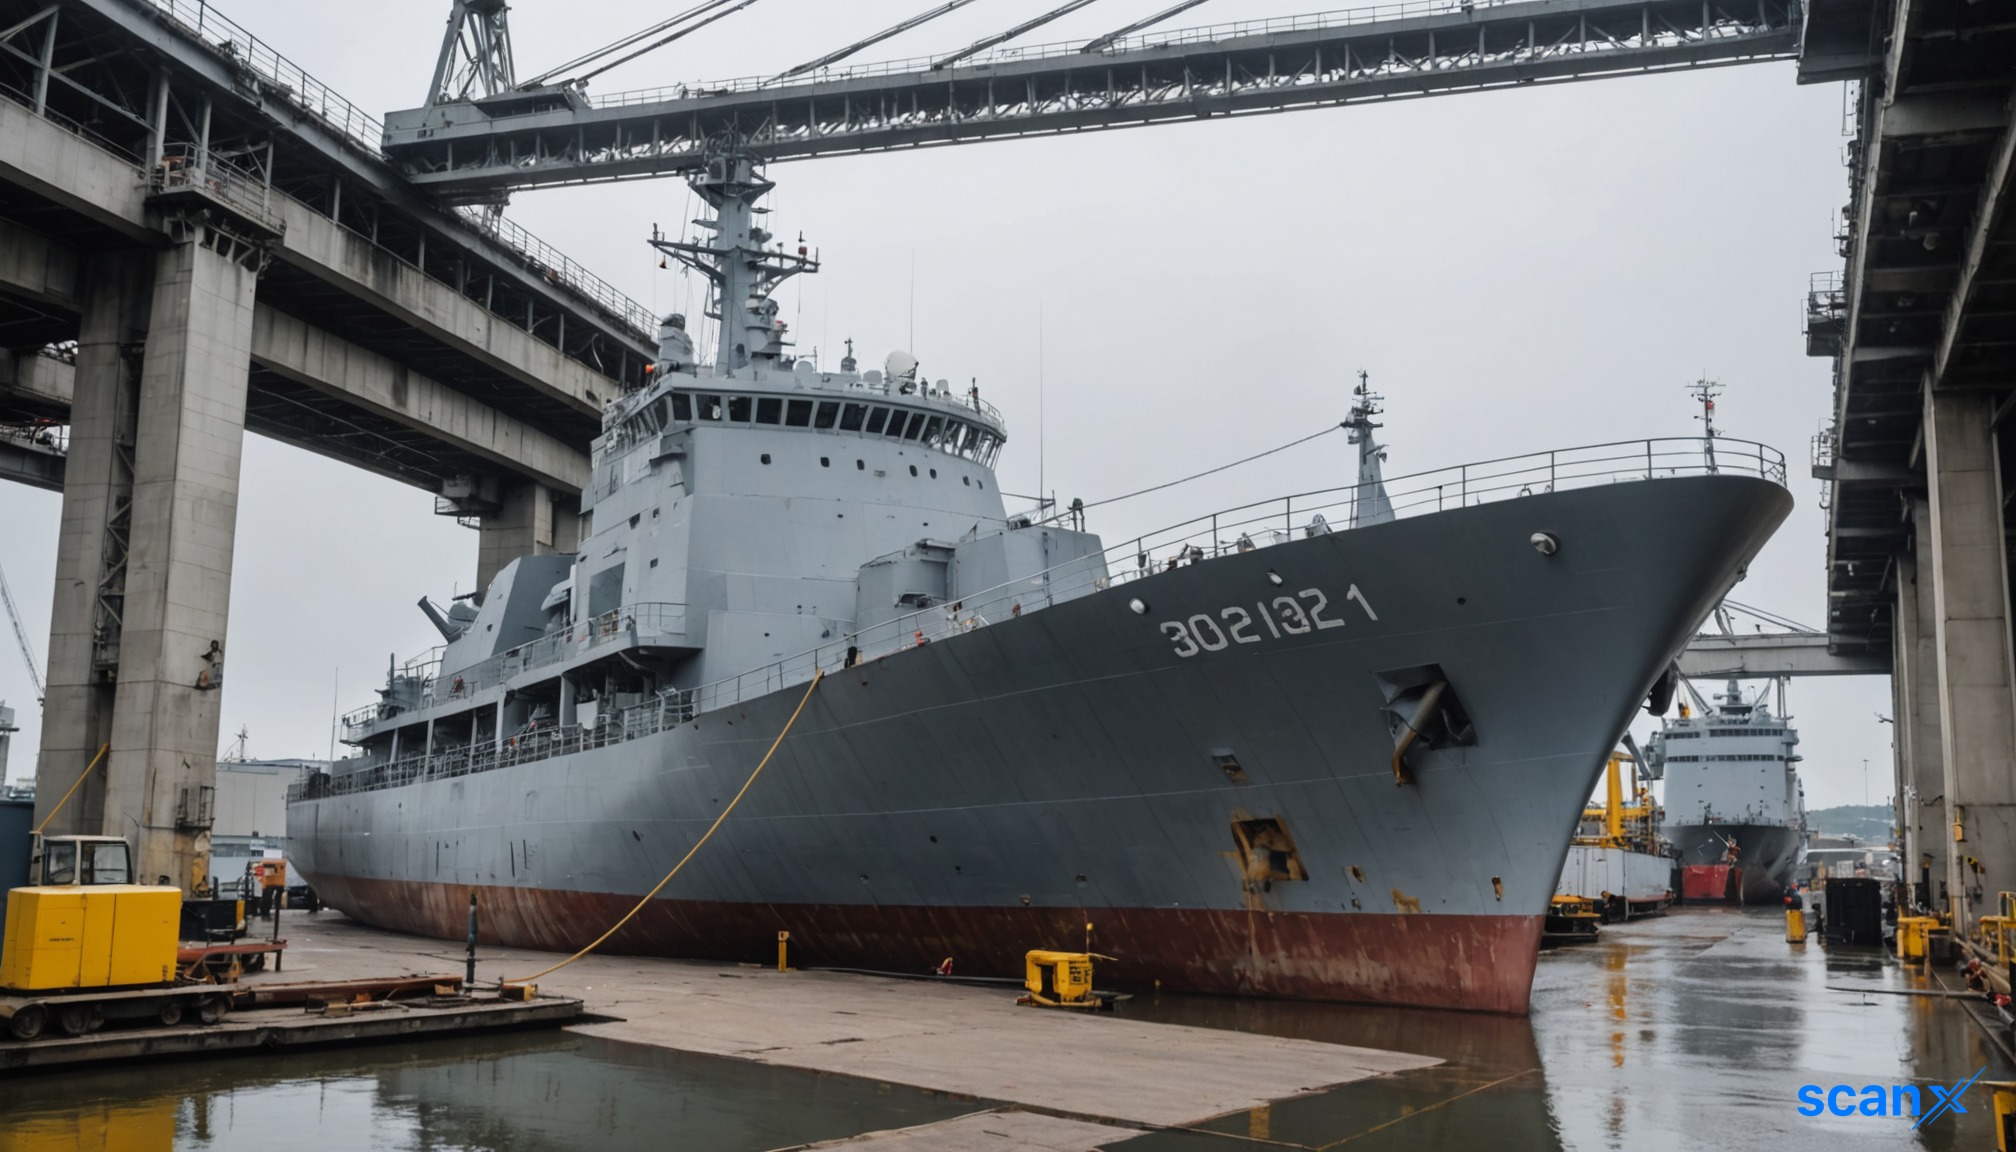
*this image is generated using AI for illustrative purposes only.

Seamec Limited has informed stock exchanges that the ONGC-owned vessel SAMUDRA PRABHA, managed by the company, was recused from its ongoing project on October 5, 2026. The vessel will undergo statutory drydocking, a mandatory maintenance procedure required for maritime safety and regulatory compliance.

The recusal took effect at 4:00 am on October 5, 2026. Seamec disclosed this development under Regulation 30 of the SEBI (Listing Obligations and Disclosure Requirements) Regulations, 2015. The filing highlights that the vessel is owned by Oil and Natural Gas Corporation (ONGC) but operated by Seamec.

Operational Details

The disclosure specifies the exact timing of the operational pause to ensure transparency regarding asset availability. Statutory drydocking is a periodic requirement for vessels to inspect hulls, replace worn components, and ensure structural integrity.

Detail Information
Vessel Name SAMUDRA PRABHA
Owner ONGC
Manager Seamec Limited
Recusal Date October 5, 2026
Recusal Time 4:00 am
Reason Statutory Drydocking

Regulatory Compliance

Seamec stated that the information was received at 11:31 am on the same day. The company requested the exchanges to take the disclosure on record. This procedural step ensures that investors are aware of any temporary reduction in fleet capacity or project execution timelines associated with specific vessels.

The filing was signed by SACHIDANANDA MOHANTY, President - Corporate Affairs, Legal and Company Secretary, confirming the authenticity of the operational update.

Historical Stock Returns for Seamec

1 Day5 Days1 Month6 Months1 Year5 Years
-1.92%-9.59%-6.83%+8.41%+71.22%+32.23%

How will the temporary unavailability of SAMUDRA PRABHA impact Seamec's current project execution timelines and potential penalty clauses with ONGC?

What is the estimated duration of the statutory drydocking, and how might this affect Seamec's fleet utilization rates for the remainder of the fiscal year?

Will Seamec deploy alternative vessels from its managed fleet to cover the operational gap left by SAMUDRA PRABHA's recusal?

Seamec wins $19.02 million charter hire order for ONGC subsea projects

scanx
Reviewed by
Ritika DScanX News Team
Key Highlights
  • Seamec secured a $19.02 million charter hire order from G R Infraprojects
  • Contract duration is 180 days for ONGC subsea projects
  • Order value represents approx 7% of average quarterly revenue
  • Disclosed order book coverage remains low at 0.08 quarters
powered bylight_fuzz_icon
52285071

*this image is generated using AI for illustrative purposes only.

Seamec has received a confirmed work order worth $19.02 million from M/s. G R Infraprojects Limited for the charter hire of the vessel "SEAMEC II". The contract is scheduled for a duration of 180 days and supports ONGC subsea projects.

Order in Financial Context

The $19.02 million order value represents approximately 7% of the company's average quarterly revenue of ₹271.55 crore. The total disclosed order book stands at ₹21.20 crore (sum of the 5 orders disclosed across the last 3 fiscal quarters shown in the table below), resulting in an order book coverage of 0.08 quarters of average quarterly revenue. This indicates that while the new order adds to the backlog, the visible pipeline covers less than one quarter of current revenue run-rate, suggesting reliance on continuous short-term contract renewals or undisclosed long-term charters for sustained visibility.

Company Order Track Record

Order inflow velocity has remained relatively stable across the last two disclosed quarters, with Q1FY27 recording ₹10.78 crore and Q2FY27 recording ₹10.42 crore prior to this new award. The current order size is significantly larger than the typical per-order size observed in the history (ranging from ₹2.12 crore to ₹6.54 crore), marking a substantial step-up in individual contract magnitude.

Quarter Total Order Inflow (₹ crore) Key Awarding Entities
Q2FY27 (Jul-Sep 2026) 10.42 M/s. Lamprell Energy Limited
Q1FY27 (Apr-Jun 2026) 10.78 Lamprell Energy Limited, Dubai; Larsen & Toubro Limited; M/s. Lamprell Energy Limited, Dubai

Execution and Revenue Quality

Seamec's quarterly performance shows stable topline revenue with slight sequential moderation in profitability metrics. Q1FY27 revenue stood at ₹316.90 crore, down from ₹330.40 crore in Q4FY26. Operating Profit Margin (OPM) declined to 41.74% in Q1FY27 from 48.66% in Q4FY26, though it remains historically strong. There are no net loss quarters in the provided data, indicating consistent execution quality.

Quarter Revenue (₹ crore) Net Profit (₹ crore) OPM (%)
Q1FY27 316.90 81.30 41.74%
Q4FY26 330.40 103.70 48.66%
Q3FY26 331.40 99.80 42.84%

Revenue Growth - Order Wins Translating to Revenue

As Seamec has sustained order wins, with a mix of charter hires and extensions from major EPC contractors like L&T and Lamprell, its annual revenue has grown from ₹682.20 crore in FY25 to ₹1,000.00 crore in FY26, representing a YoY growth of +46.6% based on the latest annual data. This significant jump aligns with the company's strategy of deploying vessels in high-demand offshore sectors.

Working Capital and Execution Capacity

The company maintains a healthy liquidity position with a Current Ratio of 1.89x and a Total Liabilities/Equity ratio of 0.43x, indicating low leverage and sufficient capacity to fund working capital requirements for existing and new contracts. While Operating Cashflow was positive at ₹321.30 crore in FY26, Free Cash Flow was negative at -₹58.10 crore due to substantial Capex of ₹379.40 crore, reflecting ongoing fleet expansion or maintenance investments.

What to Watch

  • Execution Rate: Monitor if the $19.02 million order converts to revenue within the 180-day window without delays, impacting Q3FY27 or Q4FY27 revenues.
  • Margin Quality: Watch for OPM stability on this specific contract, given the drop from 48.66% in Q4FY26 to 41.74% in Q1FY27.
  • Client Concentration: Note that G R Infraprojects is a new key client in the disclosed list, joining Lamprell and L&T; diversification away from single-client dependency is positive.
  • Backlog Visibility: With order book coverage at only 0.08 quarters, further order announcements are key to assessing long-term visibility beyond short-term charters.

Key Observations

  • Valuation check (as of September 30, 2026): P/E of 16.2x against ROCE of 18.69%. At the time of this article, valuation was pricing in execution improvement not yet visible in return ratios.
  • Cash conversion: Operating cashflow of ₹321.30 crore in FY26; however, free cash flow was negative at -₹58.10 crore due to high capex, indicating reinvestment into assets rather than immediate cash return to shareholders.

Historical Stock Returns for Seamec

1 Day5 Days1 Month6 Months1 Year5 Years
-1.92%-9.59%-6.83%+8.41%+71.22%+32.23%
Disclaimer: This article is AI-generated using data from LiveSquawk. ScanX is not liable for any inaccuracies.

How will the $19.02 million G R Infraprojects contract impact Seamec's operating profit margins given the recent sequential decline to 41.74%?

What specific capital expenditure plans are driving the negative free cash flow, and when is this fleet expansion expected to yield positive returns?

Will the diversification of clients to include G R Infraprojects reduce Seamec's historical dependency on Lamprell and L&T for future order inflows?

More News on Seamec

1 Year Returns:+71.22%