

Adroit Industries (India) IPO DRHP: ₹87.99 crore fresh issue; PAT margin at 18.69%


- Fresh issue size is ₹87.99 crore; IPO opens 23 Sep 2026 and lists 30 Sep 2026.
- Revenue grew to ₹139.94 crore in FY2026 with PAT margin expanding to 18.69%.
- Proceeds allocated to Dewas/Pithampur capex and ADPL subsidiary debt repayment.
- Key risks include 95% export dependence, unhedged FX exposure, and regulatory delays.

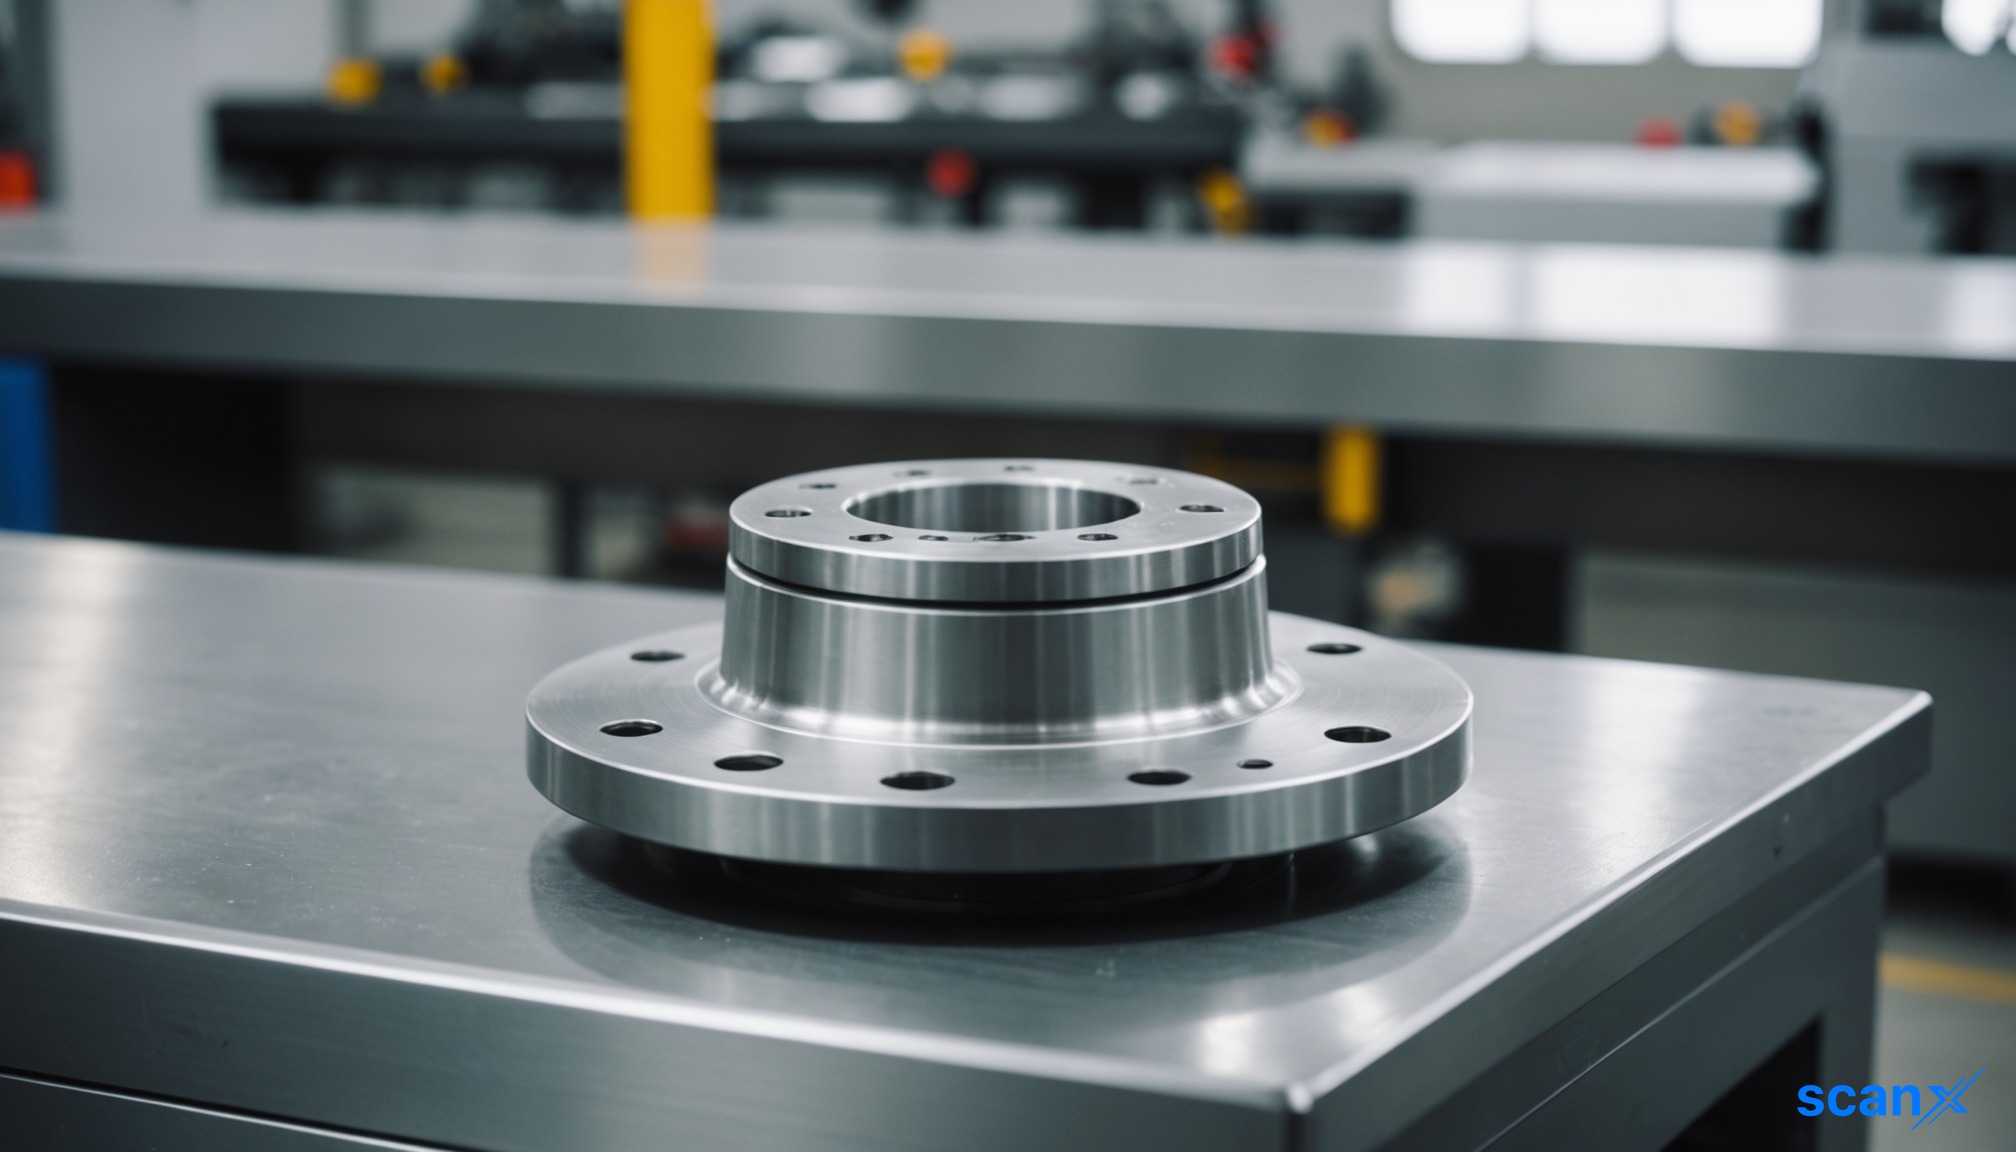

*this image is generated using AI for illustrative purposes only.
Adroit Industries (India) Limited, a vertically integrated manufacturer of propeller shafts and torque-transmission components, has filed its Draft Red Herring Prospectus (DRHP) for an initial public offering. The book-built issue comprises a identified proceeds of ₹87.99 crore and opens on 23 September 2026, with allotment scheduled for 28 September and listing on 30 September 2026.
About the Company
Founded in 1966 and incorporated in 1995, Adroit Industries operates three manufacturing facilities in Madhya Pradesh: Dewas, Pithampur, and Sanwer. The company offers over 5,250 SKUs across forging, precision machining, heat treatment, assembly, balancing, and testing. Its product portfolio includes propeller shafts, yoke components, flange components, and joint components for automotive and non-automotive sectors such as defence and heavy equipment.
The company serves 185 customers globally, with exports accounting for approximately 95% of its revenue from the sale of products in FY2026. Key markets include North America, Europe, Latin America, the Middle East, Africa, and Asia-Pacific. Adroit Driveshafts Private Limited (ADPL), an Indian subsidiary, handles downstream operations, while subsidiaries in Canada and the USA support international business.
Financial Performance
Revenue from operations grew from ₹124.53 crore in FY2024 to ₹139.94 crore in FY2026, reflecting a compound annual growth rate of approximately 6%. Profit after tax (PAT) increased significantly from ₹14.53 crore to ₹26.16 crore over the same period, with PAT margins expanding from 11.67% to 18.69%. EBITDA margin stood at 27.66% in FY2026.
| Particulars | FY2024 (₹ Cr) | FY2025 (₹ Cr) | FY2026 (₹ Cr) |
|---|---|---|---|
| Revenue from Operations | 124.53 | 133.89 | 139.94 |
| Total Expenses | 107.14 | 113.79 | 110.14 |
| Profit Before Tax | 17.96 | 22.82 | 32.90 |
| Profit After Tax | 14.53 | 18.14 | 26.16 |
The company improved its balance sheet strength, reducing the debt-to-equity ratio from 0.94x in FY2024 to 0.41x in FY2026. Return on Capital Employed (RoCE) rose from 15.07% to 19.01%. Cash flow from operations was ₹29.41 crore in FY2026.
Why the Company Is Raising Funds
The identified proceeds total ₹87.99 crore, excluding general corporate purposes. The funds are allocated as follows:
- ₹19.91 crore for capital expenditure at the Dewas facility, including machinery and equipment.
- ₹43.96 crore as investment in subsidiary ADPL for capital expenditure at the Pithampur facility.
- ₹24.12 crore as investment in ADPL for repayment or pre-payment of borrowings.
Business Strengths
- Vertically Integrated Manufacturing: End-to-end control from forging to testing reduces reliance on third-party vendors.
- Extensive Product Portfolio: Over 5,250 SKUs, representing a 37.40% increase from FY2024.
- Strong Export Presence: Exports to over 32 countries, with 95.39% of product sales revenue derived from exports in FY2026.
- Quality Certifications: Holds IATF 16949, ISO 9001, ISO 14001, and ISO 45001 certifications.
- Customer Retention: Repeat customers contributed 90.26% of revenue from sale of products in FY2026.
Key Risks
- Export and Tariff Risk: 95% of revenue is from exports, with the U.S. accounting for 53.76% of export revenue in FY2026. An additional 25% Section 232 tariff applies to U.S. exports.
- Customer Concentration: Top 10 customers contributed 60.86% of revenue from sale of products in FY2026. No long-term supply commitments exist.
- Unhedged Currency Exposure: The company has no hedging policy, resulting in net foreign exchange losses of ₹53.78 million in FY2024 and ₹38.15 million in FY2025.
- Regulatory Compliance: There have been 46+ instances of delayed statutory filings with the Registrar of Companies, with delays extending up to 3,771 days.
- EV Transition Risk: Automotive applications contributed 74.54% of revenue in FY2026. Electric vehicle architectures may reduce demand for conventional propeller shafts.
- Promoter Litigation: Promoter Mukesh Sangla is subject to criminal and tax proceedings aggregating ₹50.64 million.
Important IPO Dates
- IPO Open Date: 23-Sep-2026
- IPO Close Date: 25-Sep-2026
- Allotment Date: 28-Sep-2026
- Listing Date: 30-Sep-2026
Bottom Line
Adroit Industries presents a profile of improving profitability and deleveraging, supported by a vertically integrated manufacturing model and strong export presence. However, significant risks remain, including heavy dependence on the U.S. market amid tariff uncertainties, unhedged foreign currency exposure, and regulatory filing delays. The IPO proceeds will primarily fund capacity expansion and subsidiary debt repayment.

How will the potential expansion of Section 232 tariffs or new trade barriers in the US impact Adroit Industries' margins given its 53.76% revenue exposure to that market?
What specific strategic initiatives is Adroit Industries implementing to mitigate the risk of declining demand for conventional propeller shafts as the automotive sector accelerates its transition to electric vehicles?
Will the implementation of a formal currency hedging policy post-IPO significantly stabilize earnings, considering the historical unhedged foreign exchange losses of over ₹90 million in FY2024-25?
 17




 Create Custom Screeners
 Access 200+ Pre-built Filters
 Use 50+ Readymade Screener





