

Krishna Institute of Medical Sciences to acquire 51% stake in Insignia


- Krishna Institute of Medical Sciences approved acquiring up to 51% equity in Insignia Healthcare Private Limited
- Initial acquisition price set at ₹30.35 per share based on BDO Valuation Advisory report
- Target entity reported FY25 turnover of ₹104.5 crore but posted a loss of ₹13.28 crore
- Acquisition to be completed within 12 to 24 months via cash consideration
- KIMS currently operates the 150-bed hospital in Guntur under an O&M agreement

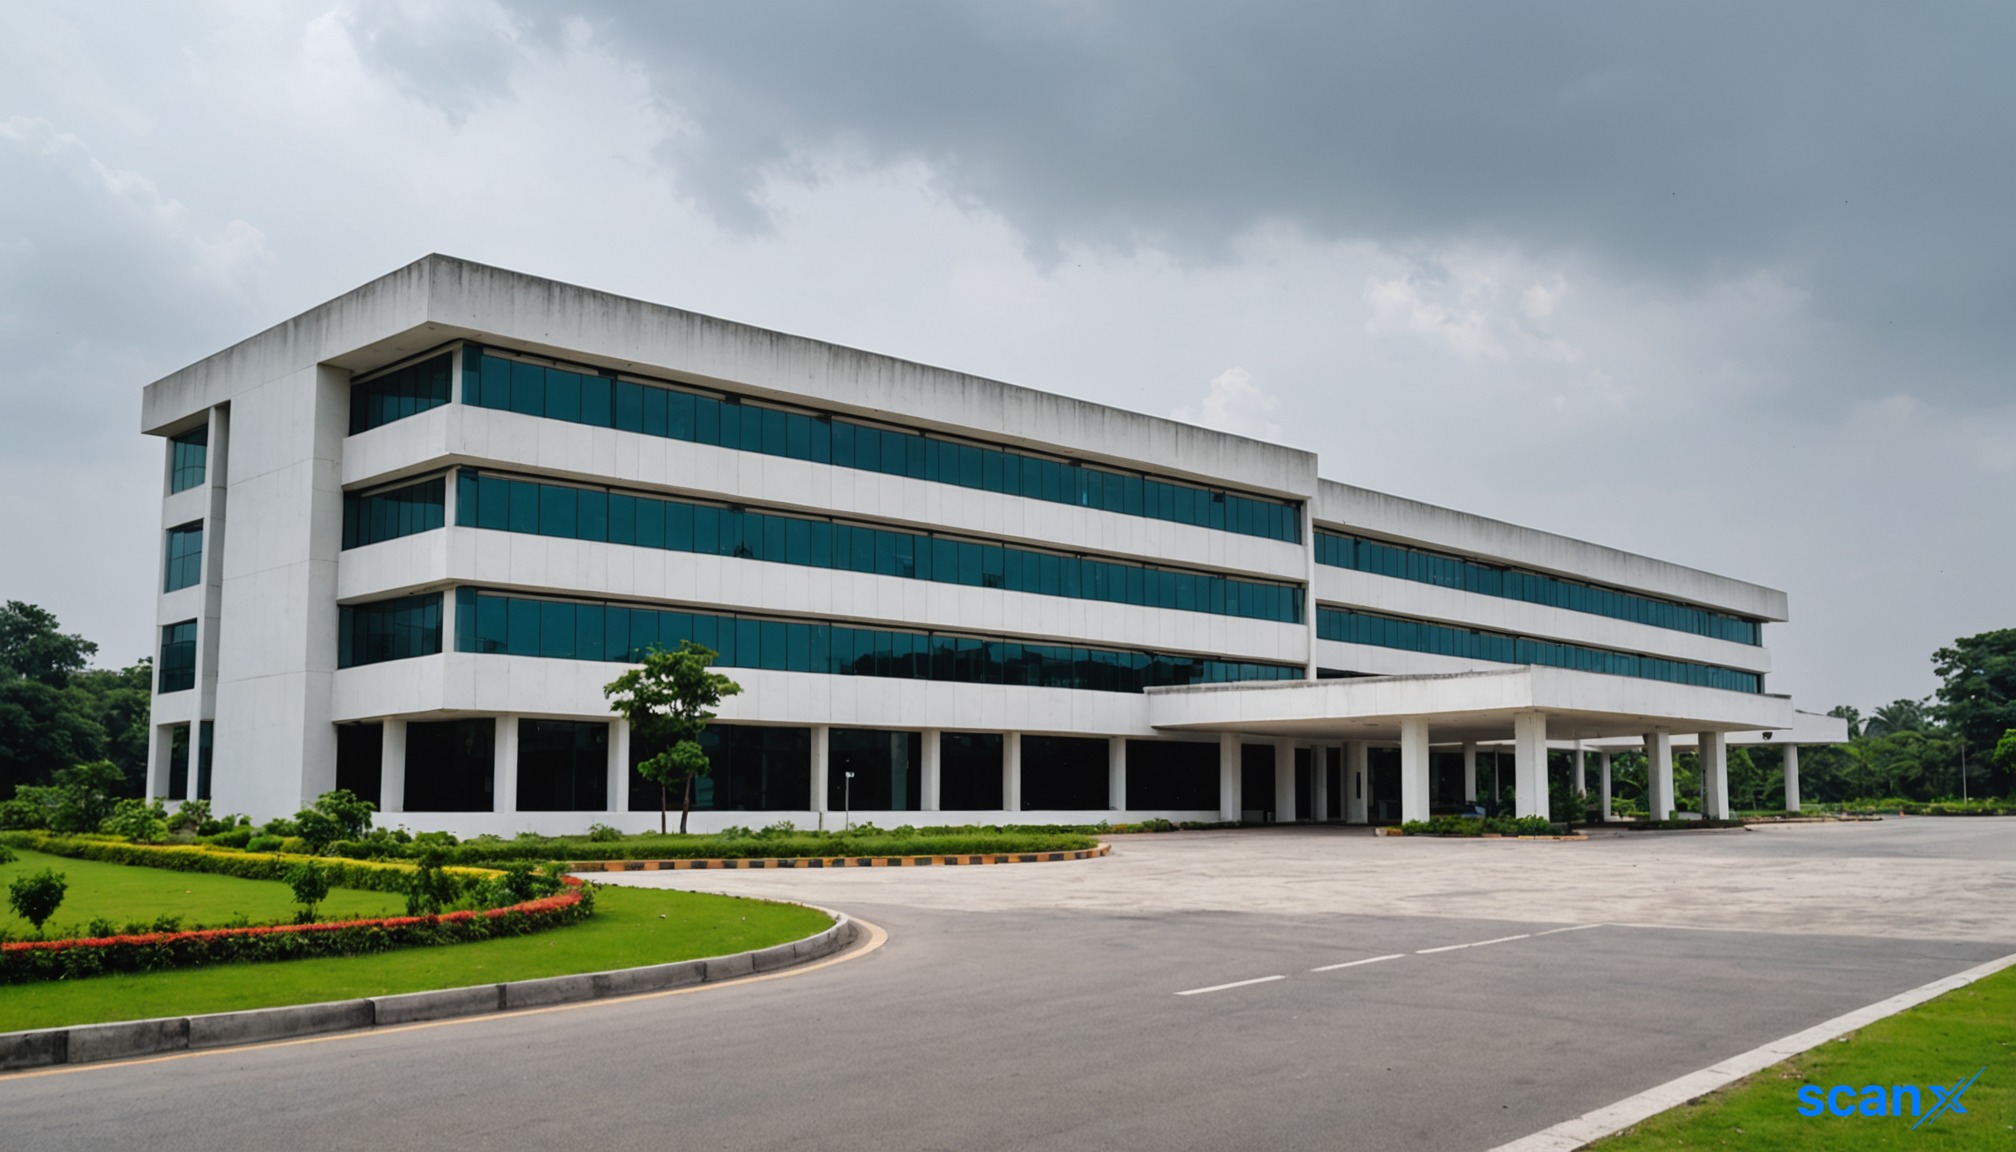

*this image is generated using AI for illustrative purposes only.
Krishna Institute of Medical Sciences Limited board approved the acquisition of up to 51% equity stake in Insignia Healthcare Private Limited on October 6, 2026. The move aims to secure operational control over a hospital facility currently managed by KIMS under an Operations and Maintenance agreement.
The target entity, Insignia Healthcare Private Limited, operates a 150-bed hospital in Guntur, Andhra Pradesh, with potential capacity expansion to 200 beds. KIMS is already engaged as the exclusive manager and operator of this facility, providing medical services through its infrastructure and clinical team.
Acquisition Details and Valuation
The acquisition will be executed via a creeping acquisition method over an indicative period of 12 to 24 months. The consideration structure is entirely cash-based. Initial shares will be acquired at ₹30.35 per equity share, based on a valuation report by BDO Valuation Advisory LLP dated October 5, 2026. Subsequent acquisitions will be priced based on independent valuations at the time of purchase.
| Parameter | Details |
|---|---|
| Target Entity | Insignia Healthcare Private Limited |
| Stake Acquired | Up to 51% on fully diluted basis |
| Consideration Type | Cash |
| Initial Price Per Share | ₹30.35 |
| Completion Timeline | 12 to 24 months |
Financial Profile of Target Entity
Insignia Healthcare has shown significant revenue growth since its incorporation in July 2018. The entity reported a turnover of ₹104.5 crore in FY25, a substantial jump from ₹0.09 crore in FY24. However, the company remains loss-making, reporting a Profit After Tax (PAT) of -₹13.28 crore for FY25 against a net worth of ₹243.3 crore.
| Financial Metric | FY25 | FY24 |
|---|---|---|
| Total Turnover | ₹104.5 crore | ₹0.09 crore |
| PAT | -₹13.28 crore | Not Disclosed |
| Net Worth | ₹243.3 crore | Not Disclosed |
What the Numbers Show
A notable divergence exists between Insignia’s rapid top-line expansion and its bottom-line performance. While turnover surged from negligible levels in FY24 to ₹104.5 crore in FY25, the entity posted a loss of ₹13.28 crore. This suggests that despite achieving significant operational scale, the hospital’s cost structure or initial setup expenses continue to outweigh revenue generation. The acquisition allows KIMS to consolidate these losses into its balance sheet while gaining full control over the asset base, which includes substantial fixed assets reflected in the ₹243.3 crore net worth.
Historical Stock Returns for Krishna Institute of Medical Sciences
| 1 Day | 5 Days | 1 Month | 6 Months | 1 Year | 5 Years |
|---|---|---|---|---|---|
| -1.71% | -9.53% | -9.25% | +10.72% | +0.44% | +185.87% |

How will the consolidation of Insignia's ₹13.28 crore annual loss impact KIMS' EBITDA margins and overall profitability metrics in the upcoming fiscal quarters?
What specific operational synergies or cost-reduction strategies does KIMS plan to implement to reverse Insignia's loss-making status following the acquisition?
How might the creeping acquisition structure over 12-24 months affect KIMS' cash flow management and capital allocation priorities for other expansion projects?
 19







 Access 50+ Readymade Screeners
 Use 200+ Custom Filters
 Get Full Market Insights





