

Atlanta Electricals FY26 Results: Revenue up 48% to ₹1,851 crore


- Revenue grew 48.8% YoY to ₹1,851.5 crore in FY26, beating the 40% target
- EBITDA margin expanded by 300 bps to 18.6%, reaching ₹344.4 crore
- Installed capacity jumped to 63,060 MVA with new units in Vadod and Ankhi
- Term loans fully repaid; operating cash flow stood at ₹184 crore
- Received PGCIL approval for 400 kV transformers and secured first order

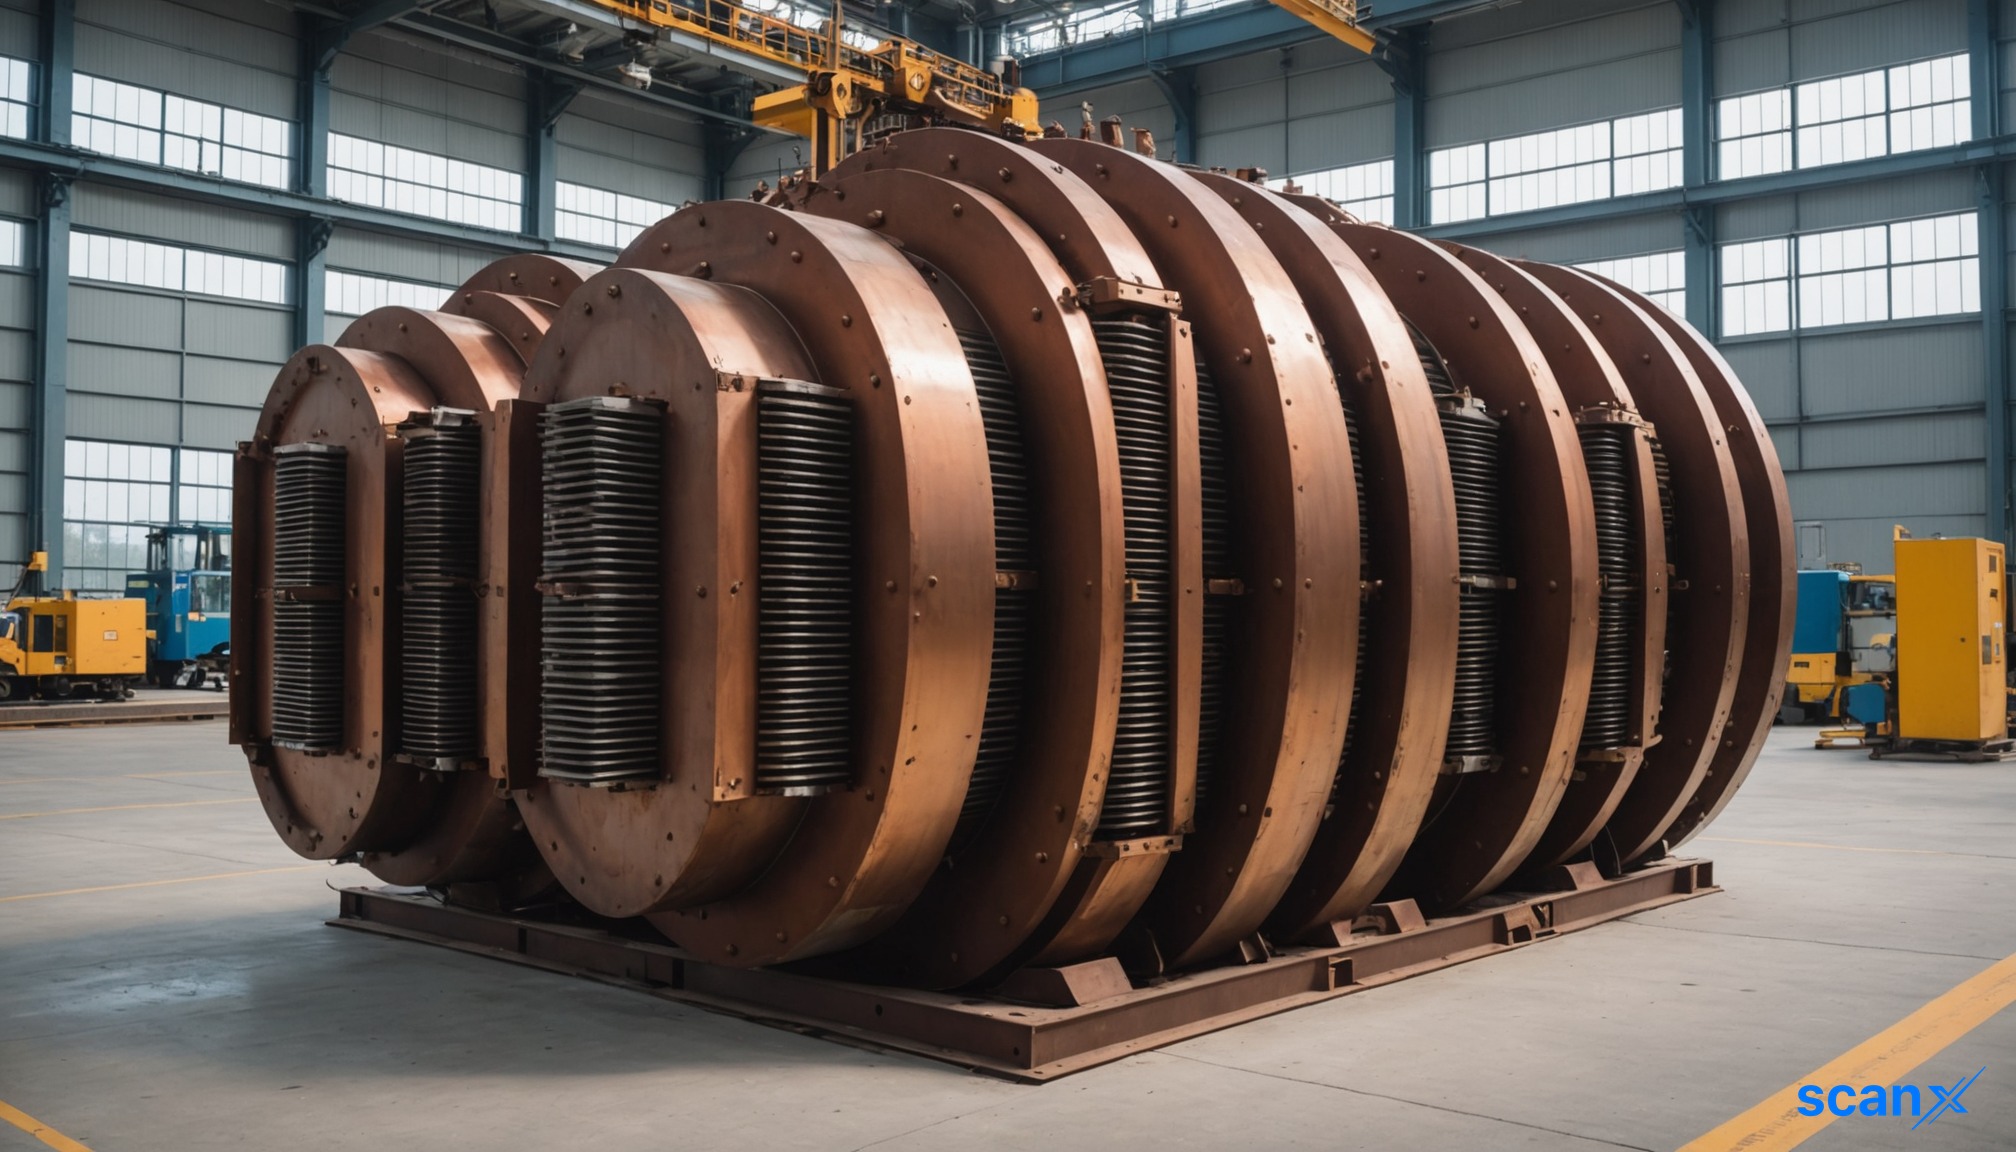

*this image is generated using AI for illustrative purposes only.
Atlanta Electricals Limited delivered its highest-ever revenue and profit in FY26, driven by volume growth and higher-voltage transformer sales. The company also fully repaid its term loans ahead of schedule.
The 38th Annual General Meeting was held on September 21, 2026, in Vallabh Vidyanagar, Gujarat. Chairman Niral Patel addressed shareholders, highlighting the transformational nature of the fiscal year following the company's listing.
Financial Performance
Revenue from operations reached ₹1,851.5 crore, a 48.8% increase from ₹1,244 crore in the previous year. This growth exceeded the company's internal target of 40%. EBITDA rose by 77.9% to ₹344.4 crore, with margins expanding by approximately 300 basis points to 18.6% from 15.6%. Profit after tax stood at ₹201.8 crore, up 70.1% year-on-year.
| Metric | FY26 | FY25 | Change |
|---|---|---|---|
| Revenue | ₹1,851.5 crore | ₹1,244 crore | +48.8% |
| EBITDA | ₹344.4 crore | Not disclosed | +77.9% |
| EBITDA Margin | 18.6% | 15.6% | +300 bps |
| Net Profit | ₹201.8 crore | Not disclosed | +70.1% |
What the Numbers Show
The divergence between revenue growth (48.8%) and EBITDA growth (77.9%) indicates significant operating leverage. The expansion of EBITDA margins by 300 bps suggests that cost efficiencies and a richer product mix contributed disproportionately to bottom-line gains compared to top-line growth.
Capacity and Order Book
Installed manufacturing capacity surged from 16,740 MVA in FY25 to 63,060 MVA in FY26. The Vadod Unit-IV facility became commercially operational, contributing approximately 6,960 MVA during seven months of operation. The Ankhi Unit-V facility added capabilities for higher-voltage transformers.
New order inflows for FY26 totaled approximately ₹2,507 crore, resulting in an unexecuted order book of ₹2,493 crore as of March 31, 2026. The company produced approximately 22,943 MVA across its five facilities during the year.
Balance Sheet and Capital Allocation
Atlanta Electricals maintained strict financial discipline, fully repaying term loans of approximately ₹340 crore ahead of schedule using IPO proceeds and internal accruals. Consequently, the term-loan balance was nil as of March 31, 2026. Operating cash flow stood at approximately ₹184 crore, while net working-capital days were approximately 64 days.
Of the ₹400 crore raised through the fresh issue, approximately ₹395.46 crore was deployed by year-end. This included ₹79.12 crore for Vadod loan repayment, ₹210 crore for working capital, and ₹85 crore for BATIPL acquisition repayment under general corporate purposes. CRISIL reaffirmed the long-term rating at A/Stable.
Strategic Outlook
The company is focusing on validating 400 kV and 765 kV transformer prototypes. It received PGCIL approval on April 2, 2026, to manufacture transformers up to the 400 kV class at Vadod, subject to final testing. The first 400 kV order has been received.
Future priorities include commissioning Unit-VI for inverter-duty transformers in FY27, adding approximately 5,000 MVA of capacity. The company aims to build exports to approximately 15% of revenue over the next three years and continue backward integration through a new tank and radiator manufacturing facility.
Historical Stock Returns for Atlanta Electricals
| 1 Day | 5 Days | 1 Month | 6 Months | 1 Year | 5 Years |
|---|---|---|---|---|---|
| +1.76% | -4.63% | -4.45% | +57.41% | +105.91% | +105.91% |

How will the successful validation and commercial rollout of 400 kV and 765 kV transformers impact Atlanta Electricals' competitive positioning against established domestic rivals?
What specific strategies is the company employing to achieve its target of increasing exports to 15% of revenue within the next three years, and which geographies are prioritized?
With the order book standing at ₹2,493 crore, what is the expected timeline for executing these orders, and how does this visibility support future capacity utilization rates for Unit-VI?
 17








 Create Custom Screeners
 Access 200+ Pre-built Filters
 Use 50+ Readymade Screener





